
Introduction
Freight factoring helps trucking companies turn unpaid invoices into fast working capital. Instead of waiting 30, 45, or 60 days for a broker or shipper to pay, carriers can receive most of the invoice value shortly after delivering a load and submitting the required paperwork. This guide explains how freight factoring works, what it costs, when it makes sense, and how to compare factoring companies beyond the advertised rate.
What is Freight Factoring?
Freight factoring is a financing solution that allows trucking companies to sell unpaid freight invoices to a factoring company in exchange for immediate cash. Instead of waiting 30 to 60 days for broker payment, carriers typically receive most of the invoice value within hours or days of delivery. This factor advances you a large percentage of the invoice value upfront, typically between 93% and 98%, and then collects payment from the broker or shipper on your behalf. When the broker pays, the factor releases any remaining balance to you, minus their fee. Because factoring is an asset purchase rather than a bank loan, it creates zero debt on your balance sheet. Approval is based on the creditworthiness of your brokers and shippers, not your years in business or personal credit score. From a cash flow standpoint, factoring compresses a 45-day payment cycle into a same-day event. The cost, the factoring fee, is predictable, recurring, and far less disruptive than a cash shortfall in the middle of an operating week.
How Freight Factoring Works
The mechanics of a factoring transaction are straightforward. Here is the sequence from load delivery to final payout.
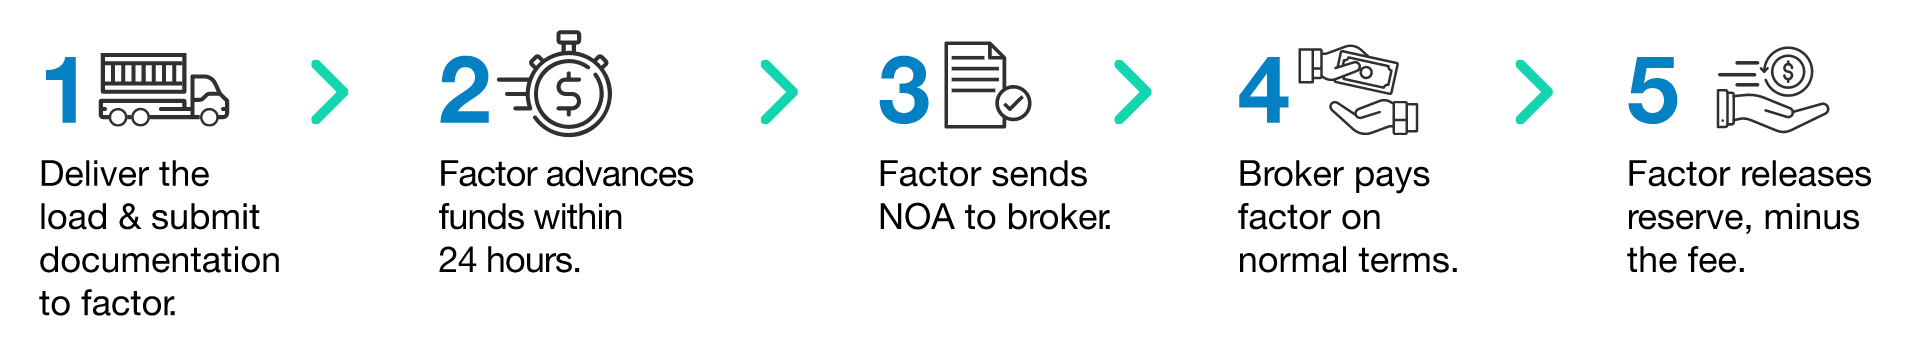
Step 1: You deliver the load and submit the signed proof of delivery (POD), rate confirmation, and bill of lading (BOL) to the factor instead of the broker/shipper. Make sure the documentation is clean and complete; it’s what determines how quickly your invoice gets funded. Missing or unclear documentation is the most common reason for delays. Most modern factoring companies accept submissions through a mobile app or online portal.
Step 2: The factor advances your funds. Once the invoice is approved, the factor deposits the advance directly into your bank account. Funding speed depends on the provider, cutoff times, and whether your paperwork is complete.
Step 3: The factor issues a Notice of Assignment (NOA) to the broker. Informing them where to send payment. Most brokers are familiar with this process and have standard workflows for paying factored invoices. It does not typically complicate the relationship.
Step 4: The broker pays the factor. The broker pays on their normal terms, whether that is net 30, net 45, or net 60. You are not involved in that collection process.
Step 5: The factor releases any reserve. If your program includes a reserve, the remaining balance is released to you once the broker pays, minus the factoring fee.
It’s simple, fast, and a lifesaver for businesses that need steady cash flow to keep operating smoothly.
What Are the Benefits of Freight Factoring?
The most obvious benefit is speed of payment. But factoring does more than accelerate your cash cycle. Here is what changes operationally when you factor invoices consistently.
Cash flow stability: Instead of an unpredictable receivables cycle, you have daily access to cash from loads you have already delivered. That predictability changes how you make decisions. You can take loads based on rate and lane fit rather than how fast a broker pays.
Credit Risk Management: Factoring gives you a gatekeeper for your freight. By running credit checks before you lock down a load, you know the broker’s credit profile and reliability upfront. This turns broker verification into a real-world risk management tool rather than an administrative afterthought.
Back-office relief: Chasing invoices, managing collections, and dealing with slow-paying brokers takes hours of administrative work. Factoring transfers that operational burden to your partner, freeing up your time to focus on dispatch, maintenance, and driving.
Debt-Free Financing: Because factoring is an asset purchase and not a bank loan, it creates no liabilities on your balance sheet. There are no principal payments, no interest accruals, and no impact on your ability to secure equipment financing later.
True Scalability: Factoring capacity grows with your invoice volume. If you double your loads in a given month, your available funding doubles accordingly. A line of credit has a ceiling that does not move with your business.
When Should I Consider Freight Factoring?
Factoring is an operational fit for carriers at several different growth stages, not a desperation tool reserved for businesses in crisis.
You should consider factoring if you face any of these operational realities:
- Extended payment delays: You are waiting more than two weeks for broker payments and that delay affects your ability to cover fuel, maintenance, or payroll. The 30 to 60 day payment window that brokers operate on exists for their benefit, not yours. Factoring shifts that dynamic without requiring you to renegotiate payment terms with every broker you work with.
- New operating authority: You are a new authority without access to a bank line of credit. Traditional lenders require operating history, tax returns, and creditworthiness that most new carriers simply do not have in their first year. Factoring approval is based on your brokers’ credit, not yours, which makes it accessible from day one.
- Rapid fleet growth: Your business is growing faster than your working capital can absorb. Taking on a second or third truck sounds like growth, but if you are waiting 45 days on every invoice while paying drivers weekly, you can run out of cash while running profitable freight. Factoring converts receivables into daily cash flow so growth does not create a liquidity crisis.
- High broker concentration: A single large broker default or slow-pay situation would threaten your entire operation. An owner-operator running five loads a week for one primary broker has concentrated payment risk. If that broker is slow to pay, everything downstream gets squeezed. Factoring transfers that risk away from your business.
- Value-added perks: You want the credit check tools, fuel card discounts, and back-office support that come bundled with modern factoring programs, even if your cash flow is currently stable. The per-load economics can be favorable even when you are not in a cash crunch.
What Is the Difference Between Recourse and Non-Recourse Factoring?
This is the most critical distinction in freight factoring, and it is also where the fine print can leave you exposed if you do not know what to look for.
With recourse factoring, your business is ultimately on the hook if a broker defaults. If an invoice hits the end of your agreement’s collection window, usually 90 days, the factor issues a chargeback. You have to repay the advance, often with an extra processing fee tacked on. Because you are carrying the financial risk, recourse programs typically offer a slightly lower advertised rate.
Non-recourse factoring works differently: the factor absorbs the loss and writes off the invoice while you keep your advance. But there is a massive catch that leads many carriers to wonder, is non-recourse factoring in trucking a myth?.
The reality is that most standard non-recourse programs only protect you if a broker files for formal bankruptcy. Real bankruptcy is rare. In the actual market, it is far more common for a broker to dispute a rate confirmation, ghost the factor, or simply shut down without ever filing legal paperwork. In those exact scenarios, traditional non-recourse programs fail, resulting in unexpected chargebacks that spike your effective factoring rate.
When evaluating partners, the right question isn’t “do you offer non-recourse?” but rather “what specific events aren’t covered, and what happens when a broker disappears without filing for bankruptcy?”
How Do I Qualify for Freight Factoring?
Qualifying for freight factoring is usually much simpler and faster than qualifying for traditional bank financing. While banks focus heavily on your financial history, tax returns, time in business, and personal credit, factoring companies primarily evaluate the quality of your invoices and the creditworthiness of the brokers or shippers responsible for payment.
This is one of the reasons freight factoring is widely used by owner-operators, small fleets, and new authorities. Even if your company is new or your credit history is limited, you may still qualify if you work with established, creditworthy brokers. In many cases, the broker’s payment profile matters more than your years in business.
The onboarding process is typically straightforward. Most factoring companies will ask for basic business and compliance documents such as your active MC authority, business registration information, proof of insurance, W-9 form, banking information for ACH transfers, and a signed factoring agreement. You will also usually provide a list of the brokers or customers you plan to work with so the factor can review their credit before approving invoices.
Because factoring is based on accounts receivable rather than long-term debt, approval timelines are often much shorter than traditional financing. In many cases, you can complete the application process within a day and begin funding invoices shortly after onboarding, as long as your paperwork is complete and your brokers meet the factor’s credit standards.
How Much Does Freight Factoring Cost?
The cost of freight factoring usually depends on your advance rate, factoring fee, and any additional service or transaction fees.
The advance rate is the percentage of the invoice value you receive upfront, while the factoring fee is the cost of getting paid faster instead of waiting 30 to 60 days for a broker or shipper to pay.
For example, if you factor a $2,500 invoice with a 3% fee, the cost of factoring that invoice would be $75. Your total cost may also vary depending on your monthly volume, broker mix, contract terms, and whether your program is recourse or non-recourse.
However, the advertised rate does not always reflect the full cost of the program. Some factoring companies charge extra for same-day ACH transfers, wires, monthly minimums, credit checks, or early contract termination. Chargebacks can also increase your real cost if your non-recourse protection is limited. That is why it is important to compare the full program, not just the lowest advertised rate.
When comparing factoring companies, the better question is not simply “What is your rate?” but “What will my total cost be once transfer fees, chargebacks, and contract requirements are included?”
What Are Common Misconceptions About Freight Factoring?
Several misconceptions about freight factoring still circulate in the trucking industry, often based on outdated assumptions or misunderstandings about how modern factoring programs actually work. While factoring is common among owner-operators, small fleets, and even larger carriers, many drivers and fleet owners still hesitate because of concerns that do not always reflect the reality of today’s market.
“Factoring means you are in financial trouble.” Factoring is a cash flow management tool, not a sign of financial distress. Many profitable carriers factor invoices because waiting 30 to 60 days for payment creates unnecessary pressure on daily operations.
“Factoring is too expensive.” The real comparison is not factoring versus zero cost. It is factoring versus the cost of cash gaps, missed loads, delayed repairs, high-interest debt, or slow broker payments.
“Non-recourse means I am fully protected.” Not always. Many non-recourse programs only cover specific situations, such as broker bankruptcy. Your actual protection depends on the contract terms and exclusions.
“All factoring contracts are long-term and restrictive.” Some factoring companies require long-term agreements or monthly minimums, while others offer more flexible programs. Terms vary, which is why it is important to compare contracts carefully.
The best way to separate myth from reality is to look at the full factoring agreement, not just the rate or the sales pitch. A good factoring program should give you faster cash flow, clear terms, practical protection, and enough flexibility to support the way your trucking business operates.
Freight Factoring vs. Other Financing Options
Factoring is not the only working capital tool available to carriers, and it is not the right answer for every situation. Here is how it compares to the main alternatives.
Business Loans Vs. Freight Factoring. A business loan provides a lump sum at a fixed cost, repaid on a set schedule regardless of revenue activity. Loans make sense for capital expenditures: a truck purchase, a major equipment upgrade, a yard acquisition. They do not work well for daily operational cash flow because repayment obligations do not flex with your freight volume. A slow month still comes with a loan payment.
Factoring has no repayment obligation because you are selling a receivable, not borrowing money. Cost scales with activity. In a strong month you factor more invoices; in a slow month you factor fewer.
| Feature | Freight Factoring | Business Loan |
| Funding source | Unpaid invoices | Borrowed capital |
| Approval based on | Broker/shipper creditworthiness | Business and personal credit |
| Funding speed | Often same day | Days or weeks |
| Creates debt | No | Yes |
| Monthly payments | No | Yes |
| Scales with sales | Yes | No |
| Best use case | Working capital and cash flow | Equipment purchases and long-term investments |
| Available for new authorities | Often yes | Often difficult |
| Impact on balance sheet | Usually, lower debt impact | Increases liabilities |
Freight Factoring vs. Lines of Credit. A line of credit is more flexible than a term loan, but it requires banking relationships, operating history, financial statements, and creditworthiness that most small carriers and new authorities do not have. Lines also come with draw limits that may not scale with your freight volume growth.
Freight Factoring vs. Quick Pay. Quick pay is a broker-offered service where the broker pays your invoice early, typically within a few days, in exchange for a discount off the invoice amount. It looks similar to factoring on the surface. The differences are significant.
With quick pay, the broker controls the terms and the timing. You accept a discount on that individual invoice with no additional services, no broker credit verification, no back-office support, and no protection against non-payment on future invoices from that broker. The discount rate for quick pay often runs higher than a factoring rate when calculated on a per-invoice basis.
Freight factoring offers a broader structure. It can provide funding across multiple brokers, support collections, include credit checks, and offer additional services such as fuel advances or back-office tools.
How to Choose the Right Freight Factoring Company
Choosing a factoring company should not be based only on the advertised rate. Two factoring programs with similar rates can create very different long-term experiences depending on the fees, support, flexibility, and protection behind the program.
Before signing, make sure the provider understands your operation, broker mix, cash flow needs, and growth plans. You should also evaluate funding reliability, broker credit check access, customer support, and the technology available to help you manage invoices and paperwork more efficiently.
Finally, review the contract carefully. Pay attention to cancellation terms, monthly minimums, termination fees, and how non-recourse protection is actually defined. A low rate may not be worth it if the agreement creates limitations or unexpected costs later on.
For a deeper breakdown of what to ask before signing, here are 5 key questions small carriers should ask freight factoring companies.
Why Choose Summar for Freight Factoring?
With over 20 years of dedicated logistics experience, Summar builds financial programs around the real-world operational needs of owner-operators and growing fleets. We eliminate the rigid constraints common in traditional factoring, offering a flexible partnership that empowers you to run your business your way.
Our standout feature is Summar Shield, an advanced credit protection program that goes well beyond standard non-recourse plans. While most factors only protect you during a formal broker bankruptcy, Summar Shield steps in to cover you if a broker disappears or delays payment for reasons outside your control. Combined with unlimited free credit checks, same-day funding before 2 PM EST and no monthly volume minimums, we give you total control over your cash flow.
We back this financial infrastructure with complimentary access to deep fuel discounts of up to $0.95 per gallon through our LoadConnex partnership. Managing your revenue is seamless with 24/7 eWallet access and a dedicated, bilingual account executive who knows your fleet and needs. At Summar, we deliver the liquidity, technology, and back-office support you need to scale confidently.
To explore what Summar’s program looks like for your specific volume and broker mix. Contact us now.
Frequently Asked Questions (FAQ)
- Is freight factoring worth it? Yes. For a 1.5% to 4% fee, you eliminate the 30 to 60 day cash gap. If waiting forces you to turn down loads, miss payroll, or run on high-interest credit cards, factoring is almost always cheaper than the cost of a cash shortage.
- Do I need good personal credit to factor? No. Factoring approval relies on your brokers’ creditworthiness, not your personal financial history. New authorities can qualify the same week their MC goes active, provided they haul for established, creditworthy brokers and shippers.
- Can I factor only some invoices? It depends on your contract. While many factors lock you into exclusivity, Summar offers flexible programs with no monthly minimums or mandatory volume requirements, letting you choose which loads to factor based on your cash needs.
- What happens if my broker does not pay? Under recourse agreements, you must repay the advance. Traditional non-recourse only covers formal broker bankruptcy. With Summar Shield, your revenue is protected if a broker ghosts or fails to pay for reasons outside your responsibility, preventing surprise chargebacks.
- How much does freight factoring cost? Standard freight fees range from 1.5% to 4% with advance rates between 93% and 98%. Always look beyond the headline rate; unadvertised transfer fees, volume penalties, and weak non-recourse chargebacks can quietly drive up your actual total cost.
- How fast will I get my funds? Clean paperwork submitted to Summar before 2 PM EST funds same day via free ACH. Submissions after the cutoff fund the next business day. Real-world funding speed depends heavily on submitting clear, complete delivery documents right from the cab.
- Will my brokers know I am factoring? Yes. Your factor sends a standard Notice of Assignment (NOA) instructing the broker to route payment to them. This is everyday practice across the logistics industry; brokers handle NOAs constantly and it never impacts your relationship or load rates.
- What is the difference between freight factoring and quick pay? Quick pay is a one-off broker service that gives you early payment on a single load for a fee. Factoring is ongoing financial infrastructure providing fuel advances, unlimited credit checks, collections management, and credit protection across all your brokers.
- Is factoring considered a loan? No. Freight factoring is not a loan. It is based on selling an invoice rather than borrowing money, so it does not create traditional debt like a business loan or require monthly loan payments.
Ready to see what freight factoring looks like for your operation? Talk to a Summar factoring specialist about your current volume, your broker mix, and what a program would cost in practice. Apply Now or call +1 (786) 406-7300